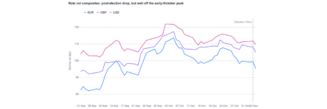
The post-election move in interest-rate volatility was visible, but it is easy to overstate. On 4 November, Parameta’s USD, EUR and GBP rate-volatility composites fell by roughly 2–4 normal-volatility basis points. Viewed alone, that drop could look like a meaningful release of event risk.
Set against the preceding two months, however, it was modest. From 1 September to their early-October peaks, composite volatility rose 23.9bp in USD, 31.2bp in EUR and 17.9bp in GBP. Even after the post-election decline, the three measures remained 11.5bp, 12.8bp and 5.7bp above their respective early-September levels. The more useful conclusion is not that uncertainty disappeared, but that the market removed a small event premium while retaining much of the autumn repricing.
The larger signal is the repricing that came before the election
For traders and risk managers, the choice of comparison window changes the message. An event-to-event view emphasises the 4 November decline. A regime view shows that implied rate volatility is still materially higher than it was two months earlier.
That distinction matters for option valuation, hedge calibration and scenario design. Treating a modest one-day fall as a return to the September environment could understate the volatility still embedded in the market. Historical comparisons, valuation marks and risk limits should therefore distinguish between a temporary event premium and a broader change in the level of uncertainty priced across the swaption surface.
EUR’s faster adjustment matters for cross-market comparisons
EUR was the most reactive composite. It rose 31.2bp into early October, briefly narrowing its discount to USD from about 11bp on 1 September to roughly 4bp on 5 October. It then fell 18.3bp from its peak, compared with declines of about 12bp in both USD and GBP, widening the EUR–USD gap back to around 10bp.
This is a reminder that a common macro catalyst does not create a uniform volatility response. Relative-value analysis needs observable, comparable benchmarks across currencies, not an assumption that each market will transmit the same shock with the same magnitude or persistence. For model governance and valuation control, the cross-currency spread can be as informative as the outright level.
GBP’s resilience argues against a one-factor explanation
GBP remained the highest of the three composites throughout the period, yet moved the least on 4 November, falling only 2.0bp. That pattern is consistent with the election acting more directly through the dollar bloc, while sterling volatility continued to reflect a different mix of domestic and global rate risks.
The practical lesson is to resist explaining an entire volatility surface with one headline. Execution timing, hedging decisions and cross-market positioning benefit from separating shared event risk from currency-specific drivers. A transparent time series makes that separation testable rather than anecdotal.
Transparent benchmarks separate event noise from regime change
Parameta’s end-of-day IRS Volatility Indices express swaption implied volatility in normal basis-point terms across option expiries and underlying swap tenors, with an “ALL/ALL” composite providing a broad view of each available currency surface. Used over time, composites help practitioners distinguish a brief event adjustment from a lasting regime change. The post-election decline matters, but the larger message is that rate-volatility pricing remains well above early-September levels. To explore the underlying cross-currency series and surface data, request a Parameta data sample.
Disclaimer
© 2026 ICAP Information Services Limited (“IISL”). This communication is provided by ICAP Information Services Limited or a member of its group (“Parameta”) and all information contained in or attached hereto (the “Information”) is for information purposes only and is confidential. Access to the Information by anyone other than the intended recipient is unauthorised without Parameta’s prior written approval. The Information may not be not used or disclosed for any purpose without Parameta’s prior written approval, including without limitation, storing, copying, distributing, licensing, selling or displaying the Information, using the Information in an application or to create derived data of any kind, co-mingling the Information with any other data or using the data for any unlawful purpose of for any purpose that would cause it to become a benchmark under any law, regulation or guidance. The Information is not, and should not be construed as, a live price, an offer, bid, recommendation or solicitation in relation to any financial instrument or investment or to participate in any particular trading strategy or constituting financial or investment advice or a financial promotion. The Information does not constitute a public offer under any applicable legislation or an offer to sell or a solicitation of an offer to buy any securities. The Information is not to be relied upon for any purpose whatsoever and is provided “as is” without warranty of any kind, either expressly or by implication, including without limitation as to completeness, timeliness, accuracy, continuity, merchantability or fitness for any particular purpose. All representations and warranties are expressly disclaimed, to the fullest extent possible under applicable law. In no circumstances will Parameta be liable for any indirect or direct loss, or consequential loss or damages including without limitation, loss of business or profits arising from the use of or any inability to use the Information, or any inaccuracy in the Information. Parameta may suspend, withdraw or modify or change the terms of the provision of the Information at any time in its sole discretion, without notice. All rights, including without limitation intellectual property rights, in and to the Information are, and shall remain, the property of IISL or its licensors. Use of, access to or delivery of Parameta’s products and/or services requires a prior written licence from Parameta or its relevant affiliates. The terms of this disclaimer are governed by the laws of England and Wales.