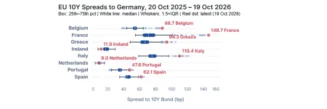
European government-bond spreads are not moving uniformly. The latest observation for France is 146.7 basis points over Germany, the widest among the eight markets shown and far beyond France’s one-year interquartile range. Italy, Greece and Belgium are also above their typical ranges, but France’s separation is materially larger.
That matters because an extreme spread is more than a higher financing cost. It can indicate that established pricing relationships are being reassessed—and that market participants may need to revisit assumptions embedded in execution, valuation, and risk models.
A distributional break can matter more than the absolute level
The chart places each latest spread within its own one-year distribution, covering 20 October 2025 to 19 October 2026. This context distinguishes an ordinary move inside a familiar range from a potential shift in market regime. France’s latest spread is roughly twice its visually indicated median, while the Netherlands remains close to its median and Ireland is below its own.
Recent student protests in France are one current event contributing to uncertainty and wider French bond spreads. However, a balanced assessment should not attribute a distributional break to a single headline. Fiscal expectations, political stability, issuance dynamics, liquidity conditions, and changes in investor positioning can reinforce one another.
The practical question is therefore not simply what happened, but whether the market is repricing a temporary event or a more persistent risk premium.
Relative-value assumptions may need to be recalibrated
When one sovereign moves far beyond its historical range, relationships that appeared stable can weaken. Hedging a French position with a broad euro sovereign basket, for example, may leave more basis risk than a model calibrated during calmer periods suggests. Relative-value strategies can also become more sensitive to timing, liquidity, and the choice of reference instruments.
For valuation teams, the dispersion shown across countries highlights the limitations of using a generic regional adjustment. France at 146.7 basis points and the Netherlands at 9.0 basis points are not simply different points on the same curve; they reflect materially different risk and liquidity conditions.
Observable, instrument-level data can help firms test whether curves, liquidity premiums and scenario assumptions still reflect executable market levels.
Transparency supports better decisions during dislocation
Outliers deserve attention, but they also require context. Distributional analysis helps practitioners see whether the latest observation is typical, elevated, or exceptional relative to recent history. That perspective can improve trade evaluation, challenge stale model parameters, and support more disciplined conversations between trading, risk and valuation teams.
The key takeaway is not that every spread outside its recent range will remain there. It is that historical relationships should not be treated as fixed when the evidence indicates a break. Transparent and observable spread data gives practitioners a stronger basis for determining whether a move represents noise, event risk or a broader repricing of sovereign credit and liquidity.
To explore the underlying observations and compare spread distributions across European sovereign markets, request a data sample from Parameta Solutions.
Disclaimer
© 2026 ICAP Information Services Limited (“IISL”). This communication is provided by ICAP Information Services Limited or a member of its group (“Parameta”) and all information contained in or attached hereto (the “Information”) is for information purposes only and is confidential. Access to the Information by anyone other than the intended recipient is unauthorised without Parameta’s prior written approval. The Information may not be not used or disclosed for any purpose without Parameta’s prior written approval, including without limitation, storing, copying, distributing, licensing, selling or displaying the Information, using the Information in an application or to create derived data of any kind, co-mingling the Information with any other data or using the data for any unlawful purpose of for any purpose that would cause it to become a benchmark under any law, regulation or guidance. The Information is not, and should not be construed as, a live price, an offer, bid, recommendation or solicitation in relation to any financial instrument or investment or to participate in any particular trading strategy or constituting financial or investment advice or a financial promotion. The Information does not constitute a public offer under any applicable legislation or an offer to sell or a solicitation of an offer to buy any securities. The Information is not to be relied upon for any purpose whatsoever and is provided “as is” without warranty of any kind, either expressly or by implication, including without limitation as to completeness, timeliness, accuracy, continuity, merchantability or fitness for any particular purpose. All representations and warranties are expressly disclaimed, to the fullest extent possible under applicable law. In no circumstances will Parameta be liable for any indirect or direct loss, or consequential loss or damages including without limitation, loss of business or profits arising from the use of or any inability to use the Information, or any inaccuracy in the Information. Parameta may suspend, withdraw or modify or change the terms of the provision of the Information at any time in its sole discretion, without notice. All rights, including without limitation intellectual property rights, in and to the Information are, and shall remain, the property of IISL or its licensors. Use of, access to or delivery of Parameta’s products and/or services requires a prior written licence from Parameta or its relevant affiliates. The terms of this disclaimer are governed by the laws of England and Wales.
Latest Insights
See All
MAS Enforces "Operational Reflex" in New Liquidity Risk Guidelines for Banks
Navigating Risk and Regulation in Asia’s Expanding OTC Markets